Carbon credit markets have advanced into the stage that they are no longer just about offsets and allowances changing hands bilaterally. As a matter of fact, over the past few years, derivatives tied to carbon—futures, options, and exchange-cleared contracts—have scaled dramatically. Exchanges and trading houses are building infrastructure that turns carbon into a tradeable, hedgable, and investable commodity. That shift opens new capital and liquidity to finance decarbonization, but it also raises a hard question: is this healthy financialization that deepens the market, or a speculative layer that distorts climate outcomes?
This article explains how carbon derivatives have emerged, why institutional players are piling in, the benefits and pitfalls of financialization, and what market participants should watch in 2025 and even beyond into 2026.
What are carbon derivatives — and why do they matter?
A carbon derivative is a financial contract whose value is linked to the price of a carbon instrument-typically allowances from compliance systems (like EUAs) or standardized voluntary credits. Derivatives include futures (agreements to buy/sell at a future price), options (rights to buy/sell), and swaps. They let market participants hedge price risk, speculate on future allowance scarcity, or lock in prices for budgeting and project financing.
Derivatives matter because they introduce liquidity, enable price discovery, and allow large buyers (utilities, airlines, corporates) and traders to manage exposure. They also create standardized instruments that institutional investors and banks can underwrite and trade on regulated venues—bringing scale to what was once fragmented and opaque.
$1 Trillion+
National Value of environmental futures & options tradded in 2024
20.4 million contracts traded on ICE alone – 40% year-over-year
Evidence of a rapid build-out in 2024–25
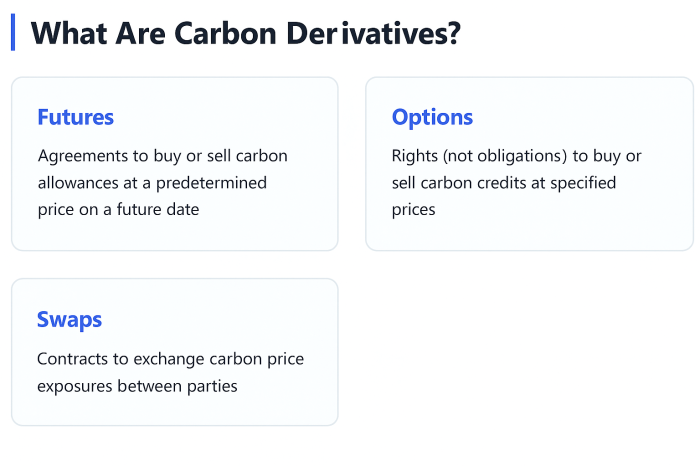
The pace of adoption is striking. Intercontinental Exchange (ICE) reported a record 20.4 million environmental futures and options contracts traded in 2024-about a 40% year-over-year increase and equivalent to more than $1 trillion in notional value. That surge signals both rising participation and growing reliance on exchange-cleared carbon tools.
Major derivatives venues are also expanding product sets. In October 2024 the CME Group launched futures on Australian Carbon Credit Units (ACCUs) via its CBL partnership, enabling block trades and cleared positions tied to standardized voluntary credits. The launch was followed by initial block trades, demonstrating market appetite.
Meanwhile, futures and options on compliance allowances—most notably EU Allowances (EUAs)—have become core trading instruments on EEX, ICE and CME, with open interest and volumes rising as EU policy tightened caps and broadened sectors covered. Exchanges regularly publish high volumes and growing open interest, underscoring the institutionalization of carbon as an asset.
Finally, regulators are waking up. U.S. oversight bodies signaled new guidance in 2024–25 to strengthen rules around carbon-related derivatives and the underlying credits—aimed at preventing fraud, improving transparency, and protecting markets. That regulatory attention reflects carbon derivatives’ growing systemic importance.
Why financialization can be progress
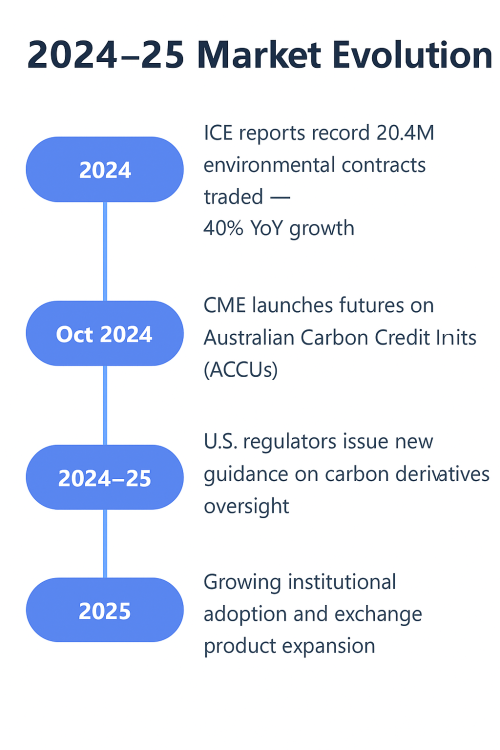
- Liquidity and price discovery. Derivatives enable continuous trading, which helps reveal market prices that reflect real-time supply/demand and policy expectations. Better price signals help governments, firms, and financiers plan decarbonization strategies and capital allocation.
- Hedging and risk management. Utilities, heavy industry and airlines can hedge future carbon costs, smoothing cash flows and making long-term investment in low-carbon tech more bankable. For project developers, price hedges can de-risk revenue streams tied to future credit sales.
- Institutional capital mobilization. Pension funds, insurers and asset managers prefer standardized, cleared instruments. Derivatives open up carbon exposure to large pools of capital that can accelerate project financing and scale carbon removal deployment.
- Market standardization. Exchange-listed derivatives require clear contract specs, delivery mechanisms and settlement rules—raising standards for contractibility and deliverability of underlying credits.
Collectively, these forces can help transform tiny, fragmented carbon markets into robust financial markets that channel capital into verified emissions reductions-if integrity is protected.
Why financialization also brings risks
Brands must avoid overclaiming. The most effective messaging:
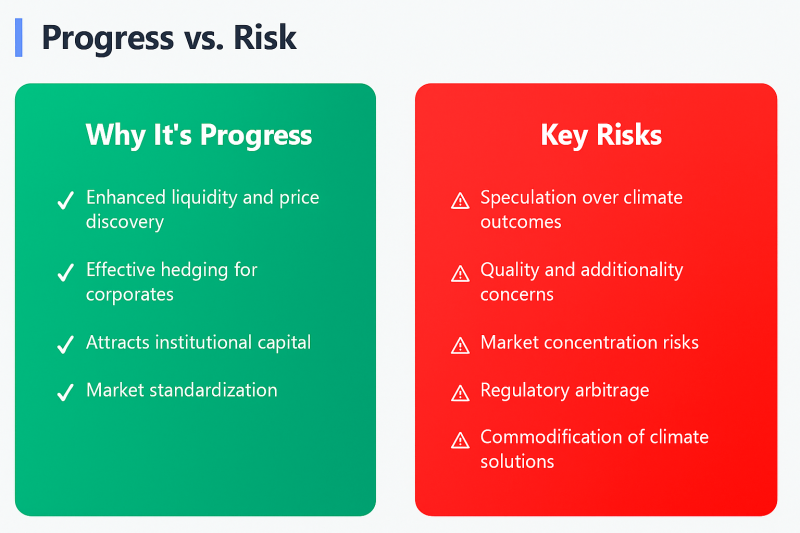
- Speculation vs. climate outcomes. Financial players seeking returns may amplify price swings that disconnect credit prices from the underlying environmental supply/demand fundamentals, potentially inflating costs for regulated entities or encouraging low-quality credit production.
- Quality and additionality concerns. Tokenizing or standardizing voluntary credits into derivatives risks legitimizing credits of uneven integrity; if low-quality credits become tradable en masse, buyers may mistakenly rely on them for compliance or claims. Independent audits and screening must keep pace.
- Market concentration and systemic risk. If liquidity concentrates among a few clearing members or traders, abrupt shocks (policy reversals, large position unwinds) could cause market stress that spills into compliance systems.
- Regulatory arbitrage. Fragmented rules across jurisdictions create arbitrage opportunities—traders may exploit inconsistencies between registries, undermining both prices and environmental accounting.
- Commodification of climate solutions. Critics argue that turning carbon into a tradable commodity may prioritize financial returns over long-term ecological stewardship, sidelining non-market values such as biodiversity and community rights. Academic analyses urge caution about overreliance on market mechanisms as climate policy.
How the market and policy response is shaping up
The good news: both market participants and regulators are already responding. Exchanges and custodians are building delivery and settlement systems tied to vetted registries; platforms like CBL/Xpansiv are integrating registry data to improve deliverability and traceability of offset-backed contracts.
Regulators-at least in some jurisdictions-are adding targeted oversight. The U.S. moved to clarify guidance on carbon derivatives and the integrity of offsets used in financial instruments, while EU reforms keep tightening cap schedules and compliance rules that underpin allowance prices. These interventions aim to retain the benefits of liquidity while limiting manipulation and low-quality credit proliferation.
Meanwhile, private initiatives-rating agencies for credit quality, industry codes (ICVCM/VCMI), and data providers-are emerging to rate and screen credits, improving the inputs that feed derivative markets. Buyers increasingly demand CCP-aligned or high-integrity credits for settlement and delivery, raising the bar for tradable inventory.
Practical advice for investors, corporates and policymakers (2025)
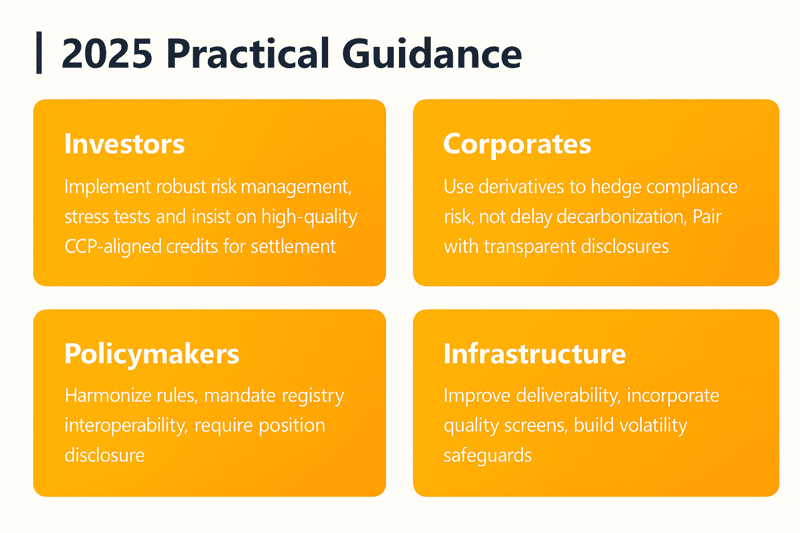
- For institutional investors: Treat carbon derivatives like any commodity exposure—implement robust risk management, stress tests for policy shocks, and insist on high-quality deliverables (CCP-aligned or registry-vetted credits). Use physical delivery contracts sparingly and prefer cleared futures/options to reduce counterparty risk.
- For corporates: Use derivatives primarily to hedge compliance risk, not to paper over delay in decarbonization. Pair any offset or derivative strategy with transparent disclosures and high-quality credit sourcing.
- For policymakers and regulators: Harmonize rules across jurisdictions where possible, mandate registry interoperability, require disclosure of large positions, and ensure independent verification of credits eligible for derivative settlement.
- For market infrastructure: Continue improving deliverability, incorporate standardized quality screens into contract specifications, and build contingency mechanisms (position limits, circuit breakers) to curb runaway volatility.
Conclusion — a conditional progress
Carbon derivatives represent real progress when they bring liquidity, transparent price signals, and financing to decarbonization. But financialization without strong integrity safeguards risks turning climate instruments into speculative assets that undermine environmental goals.
The path forward is conditional: keep building scalable, cleared markets—while enforcing quality, transparency, and alignment with climate policy. If market design, regulation, and verification improve in step with trading innovation, derivatives can be a tool for progress rather than a distraction from it.
The Bottom Line
Carbon derivatives represent conditional progress – they can channel
capital to decorbonization If paired with strong integrity safeguards,
quality standards, and aligned climate policy