The global shift away from fossil fuels toward low- or zero-carbon energy systems—is no longer a matter of policy ambition- but a market reality. As governments tighten emissions caps and companies rush to meet net-zero commitments, carbon markets have emerged as one of the most powerful mechanisms steering investment decisions.
Whether through compliance systems like the EU Emissions Trading System (EU ETS) and China’s national carbon market, or through voluntary carbon credits that support renewable energy and carbon removal projects, carbon pricing is rewriting the economics of energy.
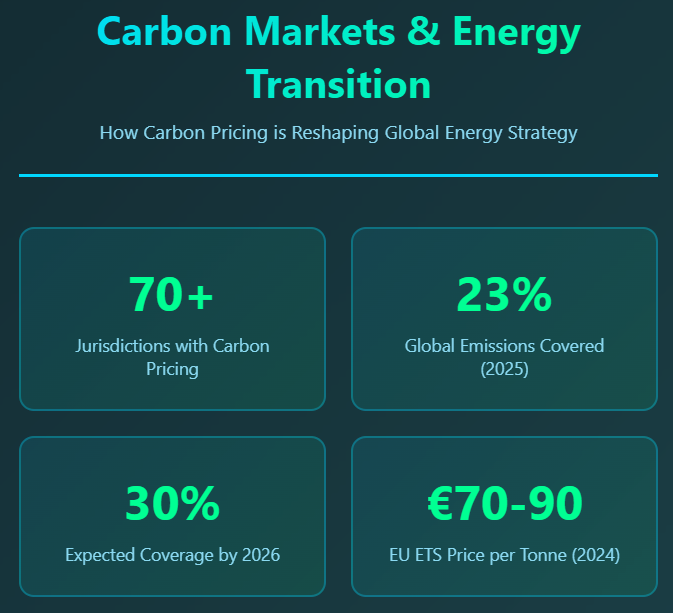
In 2025, more than 70 jurisdictions now implement some form of carbon pricing, covering roughly 23% of global greenhouse gas emissions. By 2026, that share is expected to exceed 30%, as carbon markets expand and link across regions. The message is clear: the cost of carbon is now a key input in the global energy equation.
1. From policy tool to market signal: carbon prices drive capital allocation
Carbon markets convert climate policy into economic signals that influence corporate and investor behavior. By putting a tangible price on carbon pollution, these systems make fossil-intensive operations more expensive and low-carbon alternatives more competitive.
- In the EU ETS, the carbon price averaged between €70–€90 per tonne in 2024, influencing coal plant retirements and accelerating renewables investment.
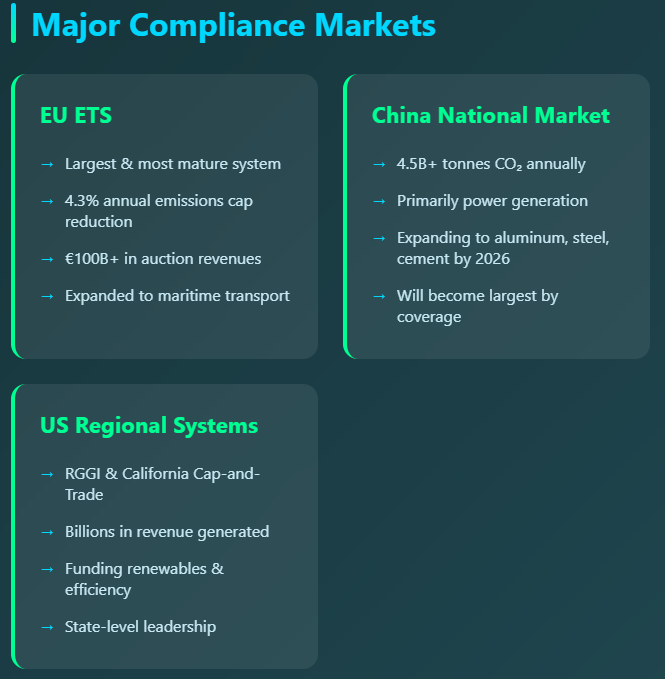
- China’s national carbon market, though still evolving, now covers more than 4.5 billion tonnes of CO₂ annually, primarily from power generation.
- In the United States, regional initiatives such as the Regional Greenhouse Gas Initiative (RGGI) and California’s Cap-and-Trade Program are generating billions in revenue for renewable projects and efficiency upgrades.
For energy companies and heavy industry, these markets serve as a cost of doing business and a guide for capital allocation. The higher and more predictable the carbon price, the faster firms shift investments toward low-carbon technologies like solar, wind, green hydrogen, and carbon capture.
2. Compliance carbon markets are driving real transformation
The backbone of the global carbon market remains the compliance sector, where emitters are legally required to hold allowances matching their emissions. The EU ETS is the largest and most mature example.
In 2024, reforms known as the “Fit for 55” package tightened the emissions cap by 4.3% per year and expanded coverage to maritime transport and new industrial sectors. This shift has:
- Accelerated coal phaseouts across Europe.
- Incentivized green hydrogen and renewable integration.
- Generated more than €100 billion in auction revenues since inception, much of it reinvested into clean infrastructure and innovation funds.
China’s compliance market, while less transparent, is poised for rapid expansion. The government plans to include aluminum, steel, and cement sectors by 2026, transforming its market into the largest by emissions coverage.
Meanwhile, emerging systems in Indonesia, South Korea, and Canada are integrating carbon pricing into national energy planning, aligning market incentives with decarbonization pathways.
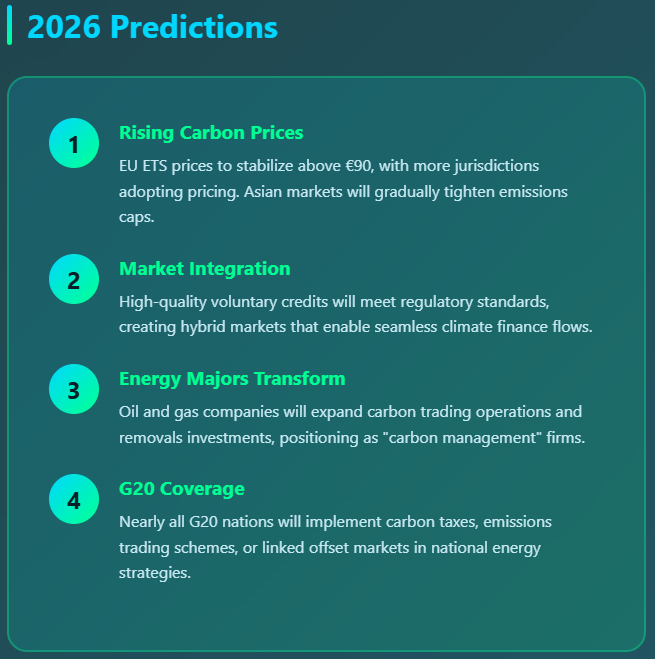
Prediction: By 2026, nearly all G20 nations will have either a carbon tax, an emissions trading scheme, or linked offset markets influencing their national energy strategies.
3. Voluntary carbon markets complement the transition
Beyond compliance markets, the voluntary carbon market (VCM) allows companies to purchase carbon credits to offset residual emissions or support climate-positive projects. While controversial at times, the VCM is an important bridge for sectors that cannot yet fully decarbonize—particularly aviation, shipping, and oil and gas.
Renewable energy projects in developing countries once dominated voluntary markets, but as many grids have grown cleaner, the focus has shifted to nature-based and carbon removal projects. Yet, voluntary credits still play a role in supporting early-stage clean energy in emerging markets where grid emission factors remain high.
For instance, voluntary carbon finance has been instrumental in:
- Funding off-grid solar projects in Sub-Saharan Africa.
- Accelerating bioenergy and waste-to-energy programs in Southeast Asia.
- Piloting carbon capture and storage (CCS) initiatives that may later qualify under compliance frameworks.
As companies transition from offsets to insets (reductions within their own value chains), voluntary carbon markets serve as testing grounds for new decarbonization models that can later inform national policy and regulation.
4. Carbon markets reshape corporate strategy and investor expectations
For corporations, carbon markets are no longer peripheral—they are integral to financial planning and disclosure. The Task Force on Climate-Related Financial Disclosures (TCFD) and International Sustainability Standards Board (ISSB) frameworks require companies to account for carbon pricing exposure.
Energy-intensive firms—utilities, cement producers, steelmakers—are now hedging carbon price risks just as they hedge fuel or currency exposure. Carbon allowances have become tradable assets, influencing share valuations and credit ratings.
Investors, too, are watching carbon exposure closely. Climate-aligned funds are favoring companies with:
- Explicit internal carbon pricing mechanisms.
- Demonstrated participation in compliance or voluntary markets.
- Low-carbon capital expenditure plans aligned with net-zero trajectories.
For example, European utilities that rapidly adapted to high carbon prices by retiring coal and investing in renewables (such as Ørsted and Enel) have seen stock outperformance compared to lagging fossil-heavy peers.
In short, carbon markets are now a proxy for climate competitiveness.
5. Energy transition investments linked to carbon revenues
Carbon pricing doesn’t only penalize emissions—it funds the transition. Governments are increasingly recycling auction revenues and offset proceeds into clean energy projects.
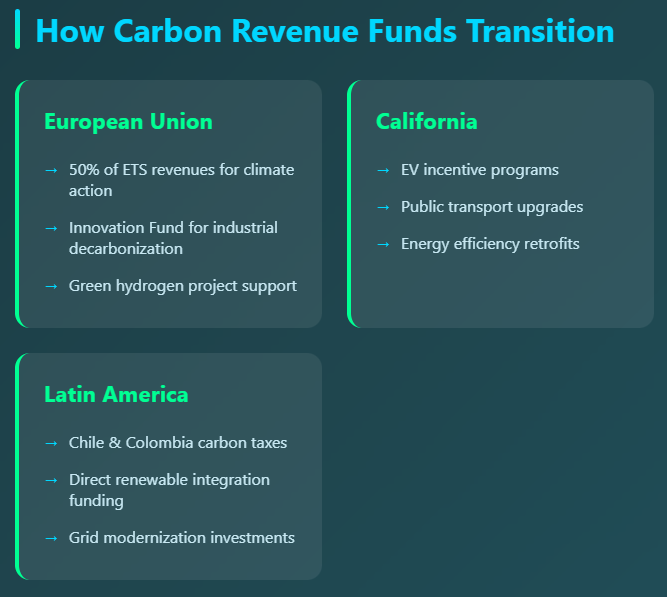
- In the EU, 50% of ETS revenues must be earmarked for climate action. The Innovation Fund supports industrial decarbonization and renewable hydrogen projects.
- In California, carbon auction proceeds finance electric vehicle incentives, public transport, and energy efficiency retrofits.
- Chile and Colombia have structured carbon taxes and offsets to directly fund renewable integration and grid modernization.
As these mechanisms mature, carbon pricing revenue becomes a steady funding source for transition infrastructure—reducing reliance on public debt or subsidies. By 2026, it is expected that global carbon markets could mobilize over $100 billion annually for clean energy investments.
6. Technology, transparency, and digital carbon markets
Technological innovation is transforming how carbon markets interact with energy systems. Digital MRV (Monitoring, Reporting, and Verification) platforms, satellite tracking, and blockchain registries now ensure higher transparency in emissions accounting.
For energy companies, these tools mean better integration of real-time carbon intensity data into operations and trading. For example:
- Smart sensors can track CO₂ intensity per megawatt-hour across power plants.
- Blockchain platforms can record the provenance of carbon credits and link them to renewable energy certificates.
- AI-driven analytics can forecast carbon price impacts on power generation portfolios.
This convergence of digital carbon infrastructure and energy analytics will make decarbonization more measurable, traceable, and investible—key to scaling private capital participation.
7. Challenges: uneven coverage, volatility, and credibility
Despite progress, carbon markets face structural challenges that could slow their impact on the energy transition:
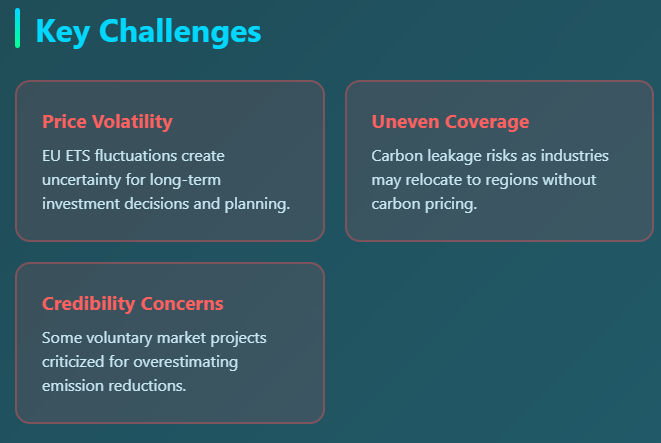
- Price volatility—as seen in 2023–2024 EU ETS fluctuations—creates uncertainty for long-term investment decisions.
- Uneven geographic coverage risks carbon leakage if industries relocate to unpriced regions.
- Credibility concerns persist in voluntary markets, with some projects criticized for overestimating emission reductions.
The solution lies in harmonization and linkage: aligning standards across borders and connecting systems to stabilize prices and improve liquidity. Initiatives under Article 6 of the Paris Agreement aim to create a more unified carbon accounting framework by 2026.
8. The road to 2026: three predictions
- Carbon prices will climb higher and spread wider. Expect more jurisdictions to adopt carbon pricing, with EU ETS prices stabilizing above €90 and Asian markets gradually tightening.
- Integration of compliance and voluntary markets will increase. As high-quality voluntary credits meet regulatory standards, hybrid markets will emerge—allowing corporate and national climate finance to flow more seamlessly.
- Energy majors will turn carbon management into a business line. Oil and gas companies will expand their carbon trading desks and invest in removals, positioning themselves as “carbon management” firms rather than pure hydrocarbon producers.
Conclusion: Carbon markets as catalysts, not just constraints
The global energy transition is accelerating, and carbon markets are no longer side mechanisms—they are central to how it happens. By internalizing the cost of emissions, they reward clean innovation, discipline polluters, and finance the infrastructure of a net-zero world.
As we move toward 2026, the most successful energy strategies will treat carbon markets not as compliance burdens but as investment opportunities—a chance to align profit with planetary stability.
Carbon markets are central to the energy transition
treating them as investment opportunities rather than compliance burdens aligns profit with planetary stability.